Best Places to Secure Bad Credit Loans California Residents Trust Today
Best Places to Secure Bad Credit Loans California Residents Trust Today
Last updated: 2026-10-16
Navigating your finances in the Golden State can often feel like trying to steer through a dense mist, especially if your credit score isn’t quite where you’d like it to be. It’s a common headache for many locals.
You might find yourself scrambling to settle an unexpected doctor’s bill or fix a busted car engine. When these emergencies strike, the massive traditional banks often slam the door shut before you even finish your sentence.
Whether you are dealing with a sudden gearbox failure while driving through Los Angeles or a shocking medical deductible in San Diego, financial emergencies rarely give you a heads-up. They just drop in like a lightning bolt.
Searching for a reliable lender means you have to look past those shiny commercials. You really need to scrutinize the fine print, the actual interest costs, and how quickly the funds land in your bank account.
Don’t let a “small monthly payment” slogan lead you down a garden path. The real sting in your pocketbook comes down to the Annual Percentage Rate (APR) combined with your repayment term.
This selection showcases the premier choices for Californians seeking versatility. These lenders offer a genuine possibility of getting approved, even if your previous financial track record has been a bit bumpy.
- OneMain Financial
- Avant
- FastLoans CA
- Upgrade
- VivaLoan
- GreendayOnline
- United Finance
Scrutinizing Lending Options for Subprime Borrowers in California
When we sat down to sort through the noise, we established a strict set of benchmarks. It wasn’t enough to just list names; we needed to know how these companies treat someone with a bruised credit history. We specifically measured the speed of deposit, the ease of the initial application, and the honesty of their terms.
You shouldn’t fly blind when applying for money. One crucial detail to uncover is whether a company intends to perform a hard credit inquiry. Knowing this upfront keeps you in the driver’s seat. You never want to be blindsided by a sudden drop in your credit rating just for asking a question.
Think of a “soft pull” as a casual glance; it tells you if you qualify without leaving a mark on your score. On the other hand, a “hard pull” is a deep investigation triggered by a formal request. This serious check can temporarily shave points off your rating, so tread carefully.
We also weighed the actual cost of borrowing against the total sum available. A massive loan limit sounds great, but it can become a trap if the interest rates are predatory. For example, taking out $5,000 at a 36% APR for 36 months is a much heavier burden than the same $5,000 loan at 15% APR. Our list favors transparency and sanity.
| Company | Borrowing Range | Transfer Time | Eligibility Criteria | Primary Benefit |
|---|---|---|---|---|
| OneMain Financial | $1,500 – $30,000 | Within 1 hour | Visit website | Local branch locations |
| Avant | Visit website | Visit website | Visit website | Versatile loan options |
| FastLoans CA | $1,000 – $35,000 | Within 24 hours | No hard credit pull | California licensed providers |
| Upgrade | Max $50,000 | Visit website | Visit website | Debit card cash back |
| VivaLoan | $100 – $15,000 | By the next day | All credit scores okay | Small loan availability |
| GreendayOnline | $100 – $5,000 | Same day service | No credit check | Rapid emergency funding |
| United Finance | Max $20,000 | Visit website | Visit website | Operating since 1922 |
Navigating the Divide Between Collateralized and Non-Collateralized Debt
When scouring your financing options, you will inevitably stumble upon two distinct categories: secured and unsecured lending. Grasping this fundamental distinction is paramount for protecting your future wealth and managing individual risk. Think of it as the thin line separating a minor financial hiccup from a catastrophic life event.
An unsecured loan, similar to personal lending options from Avant or Upgrade, operates without requiring any collateral. You won’t need to gamble your home equity or your car’s title to secure the funds. Since the bank carries more danger by lacking a physical asset to reclaim if you stop paying, the interest rates tend to climb higher.
Nevertheless, many people living in California find that avoiding the risk to their personal belongings makes this the go-to choice. It’s a trade-off between paying a bit more in interest and sleeping soundly at night. For those without much extra cushion, the freedom of an unsecured path feels like a breath of fresh air.
On the flip side, a secured loan necessitates that you pledge a specific asset, such as a savings account or a vehicle, to act as collateral. Should you fall behind on your payments, the lender holds the legal power to seize that item to recover their money. It is a heavy price to pay if things go south.
While these secured options frequently offer more favorable, lower interest rates, the danger of losing your transport can create a massive hole in your lifestyle. You must carefully balance the savings on interest against the very real possibility of losing your property. It is a high-stakes game of weighing costs against consequences.
Leading Lending Options for Californians
1. OneMain Financial
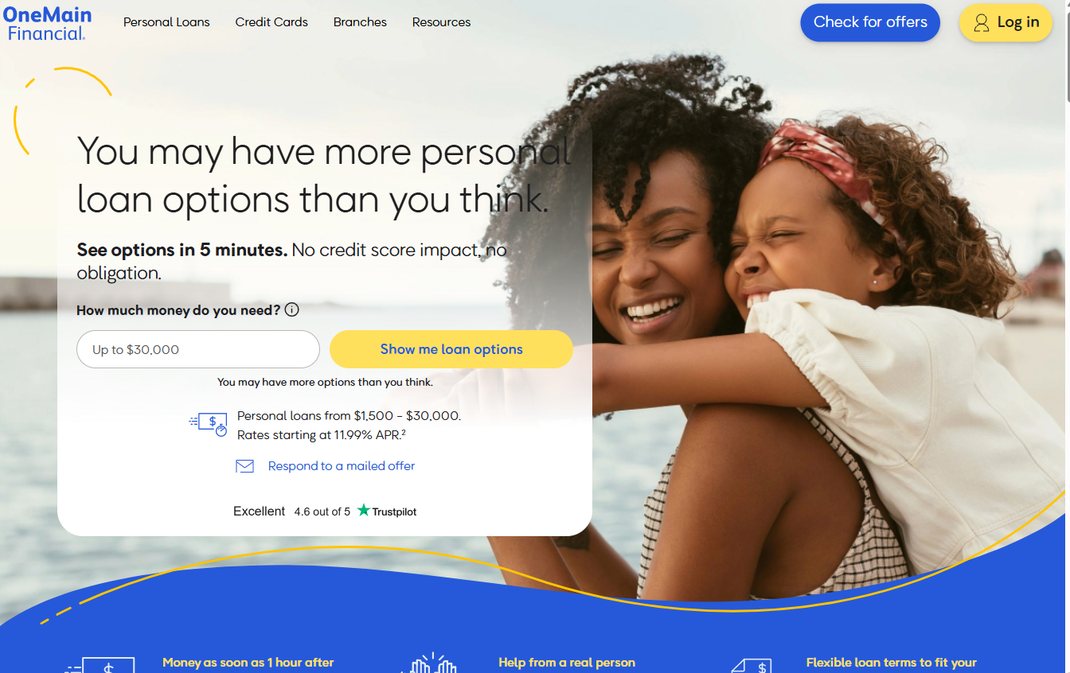
If you prefer a human touch when navigating complex paperwork, OneMain Financial might be your best bet. They maintain over 1,300 physical branches, blending modern digital tools with the ability to talk to a real person. This setup is a lifesaver if the idea of making massive financial commitments solely through a smartphone feels a bit daunting.
In bustling hubs like Fresno or Sacramento, walking into a local office can help clear up any confusion regarding loan terms. Such face-to-face interaction fosters a level of trust that many strictly digital platforms simply cannot replicate. Their personal loan offerings range from $1,500 up to $30,000, providing enough flexibility for various life events.
Borrowers can opt for fixed monthly payments over a 24 to 60-month timeline, which makes budgeting much easier to manage. Because these rates are fixed, your monthly obligation stays exactly the same even if the broader economy takes a dip. With APRs starting at 11.99%, they offer a structured path for tackling debt or unexpected costs.
Pros:
- Large network of physical locations for in-person support.
- Rapid funding, sometimes just an hour after signing.
- Predictable monthly payments simplify financial planning.
Cons:
- Requires more active engagement than digital-only lenders.
2. Avant
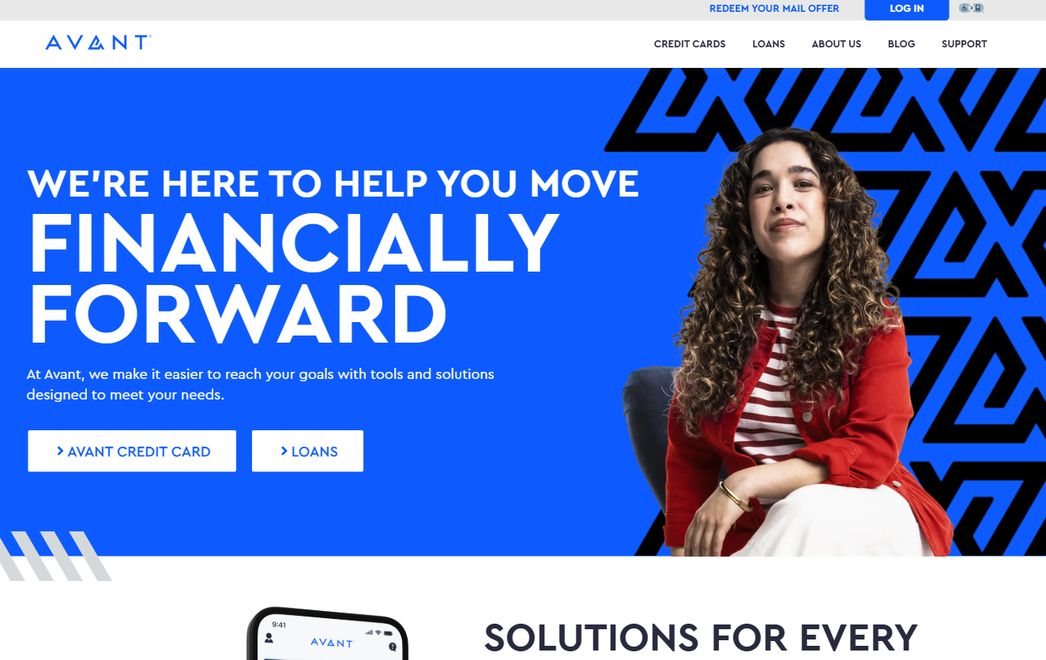
Rather than acting like a mere ATM, Avant positions itself as a partner in your financial evolution. Their toolkit is designed to help you move forward, whether that involves securing a new credit card or consolidating existing debt. Using their services feels less like a transaction and more like a long-term relationship.
This approach is a godsend for anyone looking to roll several high-interest debts into one single, manageable monthly payment. They understand that life doesn’t come in one-size-fits-all packages, so they prioritize flexibility. Their diverse product list includes everything from home improvement funds to emergency cash options.
Their platform is tailor-made for the modern, busy person who needs to handle finances during a lunch break or a commute. If you are looking for specific ways to stabilize your cash flow, their digital interface is incredibly efficient.
Pros:
- Focuses on long-term financial growth.
- Provides various products, including loans and credit cards.
- Highly intuitive digital experience.
Cons:
- Upfront transparency regarding specific rates and terms can vary.
3. FastLoans CA
When California residents find themselves in a tight spot, FastLoans CA can connect them with licensed lenders throughout the state. Speed is their specialty, often aiming to deliver funds within 24 hours to help families navigate emergencies. You can typically check your available options in just a few minutes.
When a pipe bursts or an urgent medical bill arrives, every second counts. That is where their rapid processing becomes vital. A major perk is the ability to view your options without a hard credit inquiry, which protects your score while you shop around.
With maximum loan amounts hitting $35,000, they cover everything from small repairs to larger home projects. Because they focus specifically on the California market, they are experts in local lending laws, offering an extra layer of consumer protection.
Pros:
- Checking eligibility does not require a hard credit pull.
- Extremely quick approval and disbursement cycles.
- A wide reach across many California households.
Cons:
- Interest rates may be notably higher than traditional banking.
4. Upgrade
With a massive user base of over 8 million people, Upgrade is a heavy hitter in the personal loan industry. They offer substantial sums up to $50,000, making them a top choice for major life changes or debt consolidation. If you want to swap out high-interest credit card debt for a single loan, their high limits are ideal.
They do much more than just hand out loans; they offer a full suite of financial tools, including rewards-based checking. Their checking accounts can even provide 2% cash back on your daily purchases. It is a clever way to weave your borrowing needs into your everyday banking habits.
By housing your banking and your loan under one roof, you can view your entire financial picture in one dashboard. This is a massive time-saver for anyone tired of jumping between a dozen different apps and monthly statements.
Pros:
- Generous loan limits reaching up to $50,000.
- Checking account options that offer rewards.
- Quickly check rates without impacting your credit score.
Cons:
- The best interest rates may be reserved for those with better credit.
5. VivaLoan
VivaLoan has carved out a niche for those needing smaller, more digestible amounts of cash. With minimums starting at just $100, it is perfect for those specific, small emergencies. It is an easy way to fix a sudden flat tire without drowning in a massive mountain of debt.
The entire process is built for speed, requiring only about five minutes to submit a request. Once you are approved, the money is usually sitting in your account by the next business day. It is a reliable lifeline for anyone who needs cash essentially “yesterday.”
The true strength of this service lies in its simplicity. By stripping away the red tape found at big banks, they make it much easier for people to solve immediate problems quickly and efficiently.
Pros:
- Low entry point with minimums starting at $100.
- Fast turnaround, often by the very next business day.
- Straightforward and quick application steps.
Cons:
- Maximum loan ceiling is capped at $15,000.
6. GreendayOnline
In a true crisis, GreendayOnline provides specialized installment loans that function similarly to payday loans. They specifically target individuals with poor credit by avoiding hard credit checks. For those who have been effectively locked out of the traditional banking world, this can be a vital lifeline.
Many people view this as a “last resort,” especially if they are dealing with bankruptcy or severely damaged credit. These loans range from $100 to $5,000, providing quick liquidity for immediate needs. The online application is stripped down to be as fast as possible.
While it is a high-speed solution for those needing instant cash regardless of credit history, it is still a structured product. Because these are installment loans, you repay the balance over time rather than in one lump sum, which is often easier on your monthly cash flow.
Pros:
- No hard credit checks required for the approval process.
- Possibility of receiving cash on the same day.
- Extremely simple and easy online application.
Cons:
- High interest rates are common with payday-style structures.
7. United Finance
United Finance brings a sense of seasoned reliability to the industry, having been operational since 1922. While many newer lenders are nothing more than an app on a screen, United Finance offers a history that many borrowers find reassuring. Surviving a century of economic shifts is no small feat.
They provide a variety of options, including personal loans up to $20,000 and auto loans. Their philosophy centers on making borrowing accessible and simple. For those seeking a traditional experience that prioritizes peace of mind, they remain a very solid choice.
Their long history suggests they have weathered everything from the Great Depression to modern digital shifts. This longevity can provide a sense of security for cautious borrowers who are wary of “fly-by-night” digital startups.
Pros:
- Decades of proven experience in the finance industry.
- Offers both auto and personal loan products.
- Focuses on an accessible, personalized lending approach.
Cons:
- Lacks the heavy focus on high-tech, instant digital-only features.
Maximizing Your Chances of Getting Approved
Having a low credit score doesn’t have to be a dealbreaker. There are several strategic moves you can make to pave a smoother path toward a successful loan application. While your FICO score is certainly on the radar, modern lenders often cast a wider net to see if you are a reliable borrower.
Think of it like preparing for a big job interview; being organized can make or break your first impression. By taking a moment to get your ducks in a row, you can avoid the sting of repeated rejections. You also protect yourself from unnecessary hard pulls on your credit report.
Before you dive into the digital paperwork, make sure you have your essential files ready to go. Collecting everything beforehand prevents the process from becoming a headache. You will generally require the following items:
- A government-provided identification card, such as a passport or driver’s license.
- Evidence of your California residence, like a lease or a recent utility statement.
- Verification of earnings, which might include your two latest bank statements or pay stubs.
- Your Social Security number so the lender can confirm your identity.
It is vital that your revenue stream is easy for an underwriter to track. If your work comes from gig platforms or freelance contracts, things get a bit trickier. Keeping your tax filings tidy or maintaining a steady stream of bank deposits can act as a lifesaver during the review process.
Another critical factor is your debt-to-income ratio, often referred to as your DTI. Lenders want to ensure that your monthly bills don’t swallow up too much of what you earn. They need to see that you have plenty of breathing room in your budget.
If you have a small credit card balance hanging around, consider paying it off before you hit the submit button. This minor adjustment can lower your DTI and present you in a much more favorable light. It’s a small step that could lead to a much larger victory.
Steering Clear of Financial Traps
Before you put pen to paper on any contract, you must grasp the complete price tag of your debt. It is easy to get seduced by a small monthly bill, but lengthier repayment periods can turn a minor loan into a heavy burden. You might find yourself returning much more cash than you initially requested.
Picture this scenario: you take out a $5,000 loan where the monthly installment is only $200. While that seems easy on the wallet, a 36-month term means you actually hand over $7,200 in total. That extra $2,200 represents the real price of borrowing that money.
Never settle for just the monthly figure; demand the total repayment amount in dollars. It is a simple trick that reveals the hidden weight of your obligation. Knowing the full sum helps you avoid being caught off guard by the long-term reality of your debt.
Don’t let the rush of getting cash blind you to the fine print. Some lenders like to tuck away various administrative charges or fees for paying your debt ahead of schedule. These sneaky costs can pile up and eat into your budget faster than you’d expect.
Specifically, watch out for “prepayment penalties.” These are essentially fines that lenders slap on you if you try to settle your balance early. It feels like being punished for being financially responsible, which is a major red flag in any credit agreement.
Ideally, you want the liberty to wipe out your debt ahead of time to slash interest costs without facing extra penalties. Take a moment to breathe and weigh different APRs against your lifestyle. Ensuring the loan matches your actual spending habits is the best way to prevent a massive headache tomorrow.