6 Best Land Loans for Bad Credit to Secure Your Acreage Today
6 Best Land Loans for Bad Credit to Secure Your Acreage Today
Last updated: 2026-10-17
Locating the perfect piece of earth is frequently simpler than securing the capital to acquire it. For countless visionaries, the prospect of possessing a tranquil woodland or a rural patch of paradise seems like a distant dream. Frequently, a bumpy credit history acts as a formidable barrier to entry.
Mainstream financial institutions often look down their noses when your score drops beneath specific thresholds. They typically require a down payment ranging from 20% to 30%, an amount that most novice buyers lack in their bank accounts. This creates a massive gap between aspiration and reality.
To these lenders, undeveloped soil is a volatile, high-risk asset. A house provides a physical structure that serves as collateral if a borrower defaults. Without a building, the risk is higher, making the quest for financing a steep uphill battle for many.
You must hunt for creditors who prioritize the inherent value of the terrain over a mere number on a credit report. Navigating this landscape requires knowing which lenders see the potential in the dirt. It is about finding someone willing to take a chance on your vision.
This compilation highlights ways to leap over these fiscal obstacles. Whether you seek a tiny garden, a weekend getaway, or a sprawling homestead, you must grasp your choices. The journey begins by distinguishing between various types of parcels.
You must understand the gap between a “raw land loan” for completely undeveloped space and a “finished lot” which boasts road access and utilities. Knowing this distinction is your ticket to finding the right lender. It is the foundation of your real estate strategy.
- Acorn Finance
- JetzLoan
- LightStream
- Country Bank
- Lendersa
- USDA
Our Methodology for Reviewing Land Financing
Our team scrutinized these financing choices based on how easily various credit scores could qualify. Every institution has a specific niche, so you shouldn’t assume one size fits all. It is crucial to grasp the differences between government-backed schemes, hard money, and personal loans.
Think of it like choosing a vehicle; a quick sprint isn’t the same as a long haul. While a personal loan provides a rapid cash infusion, it often carries much steeper interest rates than a standard mortgage secured by the land itself. Using the wrong tool for the job can get expensive very quickly.
On the flip side, waiting for a conventional mortgage can feel like watching paint dry, often taking 45 days to finalize. During that agonizing wait, a competitor might snatch up your perfect plot of land. We weighed how fast funds arrive against the damage a credit check might do to your score.
Finding a provider that offers soft inquiries is a total game-changer. This allows you to gauge your purchasing power without a dent in your credit history. Knowing where you stand before signing a binding contract can save you from a massive headache down the road.
Transparency was our north star throughout this investigation. We dug deep into the paperwork complexity, the pace of funding, and the specific collateral needed to seal the deal. We specifically hunted for lenders that use “soft pulls” for quotes rather than “hard pulls” that stick to your credit report.
For those living on a razor-thin margin, that distinction is everything. We didn’t just look at the numbers; we looked at the fine print to ensure no one was walking into a trap. This data helps you decide whether you need an investor’s quick fix or a stable, long-term commitment.
| Provider | Loan Ceiling | Processing Time | Credit Standing | Primary Use |
|---|---|---|---|---|
| Acorn Finance | Check website | Check website | Fair to Poor | Remodeling/Contracting |
| JetzLoan | $50,000 | 1 Day | No Hard Pull | Urgent Funds/Consolidation |
| LightStream | $100,000 | Check website | Excellent/Good | Prime Credit Users |
| Country Bank | Check website | 60-Day Lock | Conditional | Unimproved Land/Lots |
| Lendersa | Check website | Rapid Closing | Hard Money Terms | Investors/Flipping |
| USDA | Check website | Check website | Varies | Rural Projects/Housing |
Top-Rated Sources for Land Financing
1. Acorn Finance
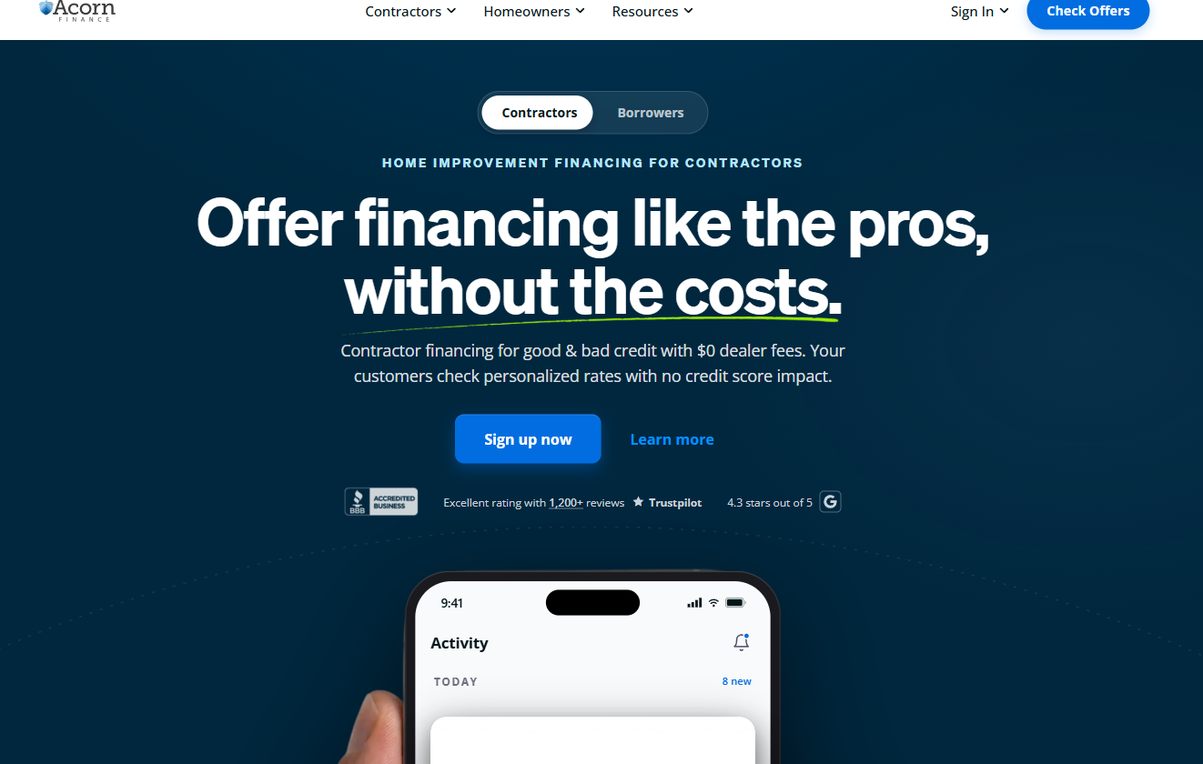
Acorn Finance serves as a vital link, connecting you with a wide array of funding possibilities. They have made a name for themselves by offering $0 dealer fees. In an industry where sneaky surcharges can balloon your total debt by thousands, this transparency feels like a breath of fresh air.
This is a fantastic resource if you plan to transform your lot immediately upon purchase. Whether you need to clear dense timber or pave a new driveway, they help bridge that gap. They are an excellent choice for those looking to upgrade their property right away.
Speed and accessibility are their hallmarks. Because they work with various lenders, they can accommodate individuals with less-than-perfect credit scores. You won’t have to face the wall of rejection typical at massive corporate banks. Instead, their diverse network helps find a specialist who can actually say “yes” to your unique vision.
Navigating financial hurdles becomes much easier with their platform. They focus on finding a match rather than just judging your history. It is a modern, flexible tool for anyone tired of the traditional banking loop of endless denials.
Pros:- $0 dealer fees for contractors and borrowers
- Customized rates without hurting your credit during the search phase
- Strong reputation with a 4.3-star rating on Trustpilot
- Interest rates might not be as low as those from prime-tier banks
2. JetzLoan
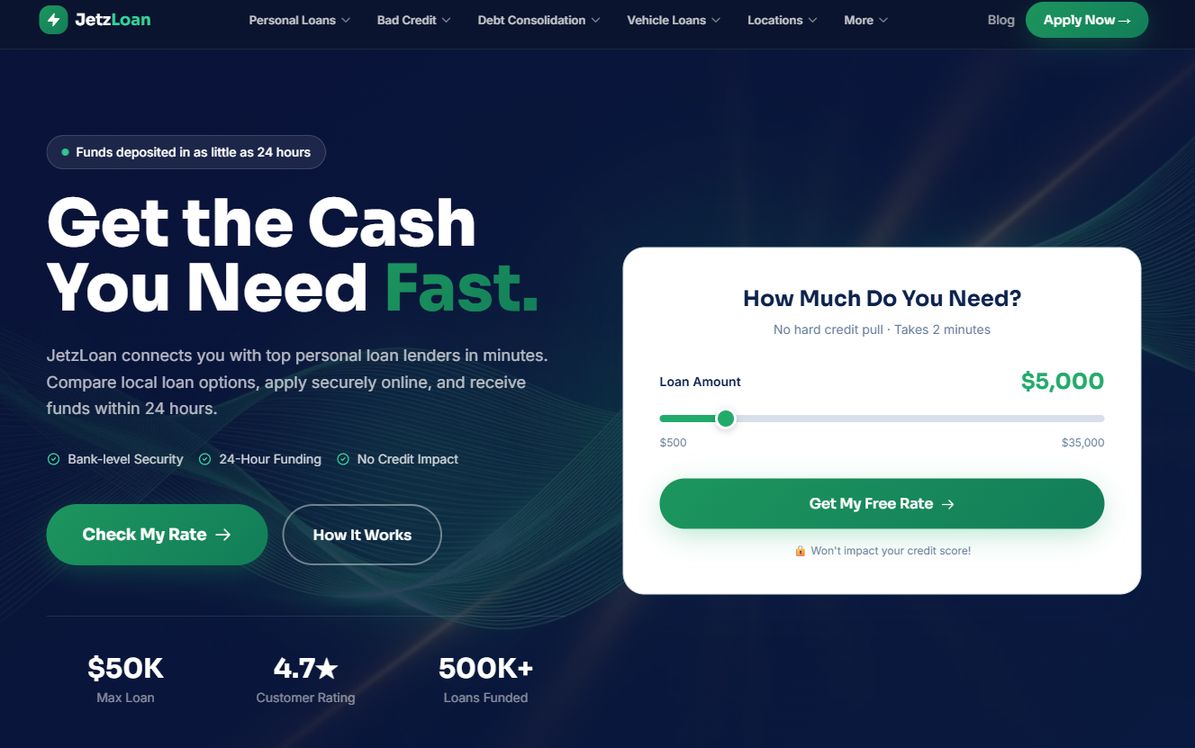
If you are racing against the clock, JetzLoan provides the velocity you need. They are capable of getting funds into your account in a mere 24 hours. This makes them an essential ally for rapid land acquisitions or when you need to consolidate existing debt quickly.
In a heated real estate market, speed is your greatest weapon. Many sellers demand cash-like terms to skip the long wait of traditional appraisals. JetzLoan helps you match that pace, ensuring you don’t lose out on a dream plot because of red tape.
Getting started is a breeze, as the application takes roughly two minutes. It is perfect for the auction winner who must prove financial strength on the spot. You can even check your potential rates without any hard credit inquiries. This allows you to shop around while keeping your credit score completely untouched.
Think of it as a high-octane solution for a fast-moving world. If your perfect lot hits the market on a Friday, you can move before the weekend is over. They fill the gap left by slower, traditional lenders.
Pros:- Funds delivered in as little as 24 hours
- Check rates without a hard credit pull
- Significant borrowing capacity up to $50,000
- Provides personal loan structures instead of standard land mortgages
3. LightStream
LightStream operates in a completely different league. Their services are specifically tailored for those who have already secured a high credit standing. If you have excellent scores, you will find their low fixed rates nearly impossible to beat. They offer a sense of premium stability for serious buyers.
With loan amounts reaching as high as $100,000, you have plenty of room to maneuver. This is ideal if you are looking at large acreage or a piece of land intended for subdivision. However, if your credit is currently struggling, this particular door will likely remain shut tight.
Their underwriting is largely automated, leaning heavily on stable income and high FICO numbers. It is a destination for the financially secure who want to avoid the expensive interest rates found in the subprime market. They turn the borrowing experience into something incredibly seamless.
If your finances are in tip-top shape, this is often your most efficient route. You can lock in your rate and enjoy the peace of mind that comes with knowing your monthly payment won’t change.
Pros:- Predictable, low fixed interest rates
- Access to large sums up to $100,000
- Strong industry reputation via Truist
- Strictly for those with good to excellent credit; not suitable for bad credit
4. Country Bank
Country Bank takes a much more personal, community-centered approach to the lending process. As an FDIC-insured institution, they offer a level of security that is vital for your peace of mind. They possess a deep understanding of rural land that major national players often lack.
A massive bank might turn you down because a lot lacks a paved road, but a local bank understands the true value of that specific soil. They comprehend local zoning and the unique potential of regional geography. This nuanced view can be a lifesaver for rural buyers.
They also offer a 60-day rate lock, providing a shield against market volatility. This allows you to hire surveyors or architects without the fear of rising interest rates sabotaging your plans. They provide customized paths for both raw acreage and ready-to-build lots.
If you want a lender who acts as a long-term partner, this is a stellar choice. Their local expertise often means the difference between a deal that falls apart and one that closes smoothly.
Pros:- 60-day window to lock in your rate
- The safety of an FDIC-insured bank
- Financing available for both buildable and raw land
- Standard banking protocols can be quite demanding
5. Lendersa
Lendersa is built for the high-speed investor who refuses to slow down. By leveraging advanced AI, they pair borrowers with a massive network of private investors and hard money lenders. This is the ultimate high-octane option for real estate pros looking to flip land or acquire development sites.
When you are competing in a cutthroat auction, you cannot afford to wait weeks for a survey to be verified. Lendersa’s system is engineered for rapid movement and quick closings. They excel in scenarios where a seller is demanding an immediate conclusion to the sale.
They cover a wide spectrum, from residential parcels to large-scale commercial properties. This diversity makes them a powerhouse for various investment strategies. If you are looking to jump into a fast-moving deal, this is your most reliable ally.
Keep in mind that these terms are not the same as a standard mortgage. While the cost might be higher, the sheer speed can be well worth the premium for a professional. It is all about how quickly you can turn that property into profit.
Pros:- AI-driven matching for optimal rates and lenders
- Built specifically for auctions and fast closings
- Services both commercial and residential property types
- Hard money terms are often significantly more costly than traditional loans
6. USDA
The USDA provides a government-backed alternative that focuses on the very heart of the nation: our rural landscapes. Their mission is to revitalize rural areas by helping people buy, fix, or build homes. This approach is designed to keep small communities vibrant and growing.
This is a phenomenal path for homesteaders or families looking to plant roots in a rural setting. Their programs are built to support those who might otherwise struggle with low down payments. They aim to expand opportunity for people who are often overlooked by traditional lenders.
If you qualify, you may find this to be one of the most affordable ways to secure property. While there is more paperwork involved and specific location rules apply, the long-term benefits are substantial. It is a program designed with people in mind, rather than just the bottom line.
It is a powerful tool for achieving the dream of homeownership. If you meet the criteria, you might find the support you need to build a life from the ground up.
Pros:- Stability provided by government backing
- Directly supports rural economic growth
- Includes a variety of grants and loan programs
- Eligibility is limited by very strict geographic boundaries
Distinguishing Property Loans from Residential Mortgages
Before you dive into the application process, you must grasp how banks categorize vacant plots compared to established houses. It is a different ballgame entirely. When a mortgage is tied to a dwelling, the structure serves as the primary collateral. If a borrower defaults, the lender simply liquidates the building to recover their capital.
Buying a piece of earth is a much more volatile proposition. Here, the collateral is nothing more than the dirt itself. If the local real estate market takes a sudden dive, that soil might plummet in value. This volatility makes lenders much more nervous about their financial exposure.
Since the stakes are higher for the bank, the terms are often steeper for you. You shouldn’t expect a low barrier to entry. It is like trying to climb a steep hill without a walking stick; you need more skin in the game to satisfy the bank’s risk appetite.
Expect to cough up a larger chunk of cash upfront. While a house might only require a small down payment, raw land often demands between 20% and 50% of the total cost. It is a heavy lift for many first-time buyers.
Interest rates for these loans tend to be higher than standard home loans. Furthermore, the paperwork trail is much longer and more winding. Banks will demand deep dives into utility access, legal easements, and how you intend to reach the property.
If you are working with hard money lenders, the terms can get even more intense. You might find yourself staring down short-term repayment windows rather than the usual thirty-year horizon. It’s a sprint rather than a marathon in those specific financial scenarios.
Smart Tactics for Closing Your Land Purchase
Before you hand over a single dime, make sure you aren’t accidentally buying a beautiful, isolated island that no one can reach. You need to perform a thorough investigation before signing any paperwork to avoid a massive headache later on.
First, never take a muddy trail for granted. A simple dirt path doesn’t guarantee you have a legal right to drive across someone else’s yard. You must confirm “legal access” to a public thoroughfare; otherwise, your property becomes a ghost parcel that no bank will touch and no buyer will want.
Next, peek under the surface by requesting a “perc test” if a septic system is in your future. If the earth refuses to drain, your dream of building a house might just evaporate. Also, keep a sharp eye on the power bill; pulling electricity to a remote site can easily run you tens of thousands of dollars.
Don’t let the quiet surroundings fool you into thinking laws don’t apply. Even in the wildest rural stretches, local ordinances dictate what you can do. You need to investigate setbacks, the minimum amount of acreage required for construction, and any rules regarding animals or sheds before you commit.
Lastly, get a professional to walk the lines. Old, leaning fences and friendly “handshake” deals with your neighbors are about as reliable as a paper umbrella in a storm. A certified survey is your only real defense to verify that the acreage you are paying for actually exists within your boundaries.
Finding a lender is a personal journey rather than a standard procedure. If you are a fast-moving investor who needs to strike while the iron is hot, a hard money lender like Lendersa might be your champion, even if interest rates are a bit steeper. On the other hand, if you are looking to plant roots for decades, a USDA program or a traditional bank might serve you better.
Many buyers fall into the trap of ignoring the “invisible” expenses that come with raw dirt. Unlike a finished home, raw land often demands an immediate cash injection for water, power, and road improvements. Make sure your loan leaves you plenty of breathing room for these vital infrastructure needs.
If you blow your entire budget on the soil itself, you might end up owning a spectacular view that you can never actually live on. It is a bitter pill to swallow when a dream property becomes nothing more than an expensive, unreachable vista.
Protect your credit score like a hawk. When you are shopping around, use services like Acorn Finance or JetzLoan that allow for no-impact rate checks. This prevents unnecessary dents to your score while you are just window shopping for the best deal.
In this business, information is your most valuable currency. Do your homework, stay patient, and make sure your financing strategy aligns perfectly with how you plan to use the dirt years down the road.